October 2, 2026
Market Review: 3Q 2026
The intersection of geopolitics and energy made for a choppy quarter as market participants digested each incremental development in the Middle East. While no clearly decisive outcome emerged, fears of escalation were ultimately unable to knock markets down.
In the face of seesawing geopolitical developments, the U.S. economy appears to be doing well. While official GDP measures for the third quarter are still several weeks out, more real time measures suggest an acceleration of economic growth. Encouragingly, there may also be signs of consumer strength broadening to lower income cohorts.
After a strong second quarter, U.S. large company stocks spent much of the third quarter consolidating. Small company stocks, which had outperformed their larger counterparts in the second quarter, turned downward. This bifurcation is partially a product of rising rates as smaller companies tend to be more sensitive to the broad interest rate environment.
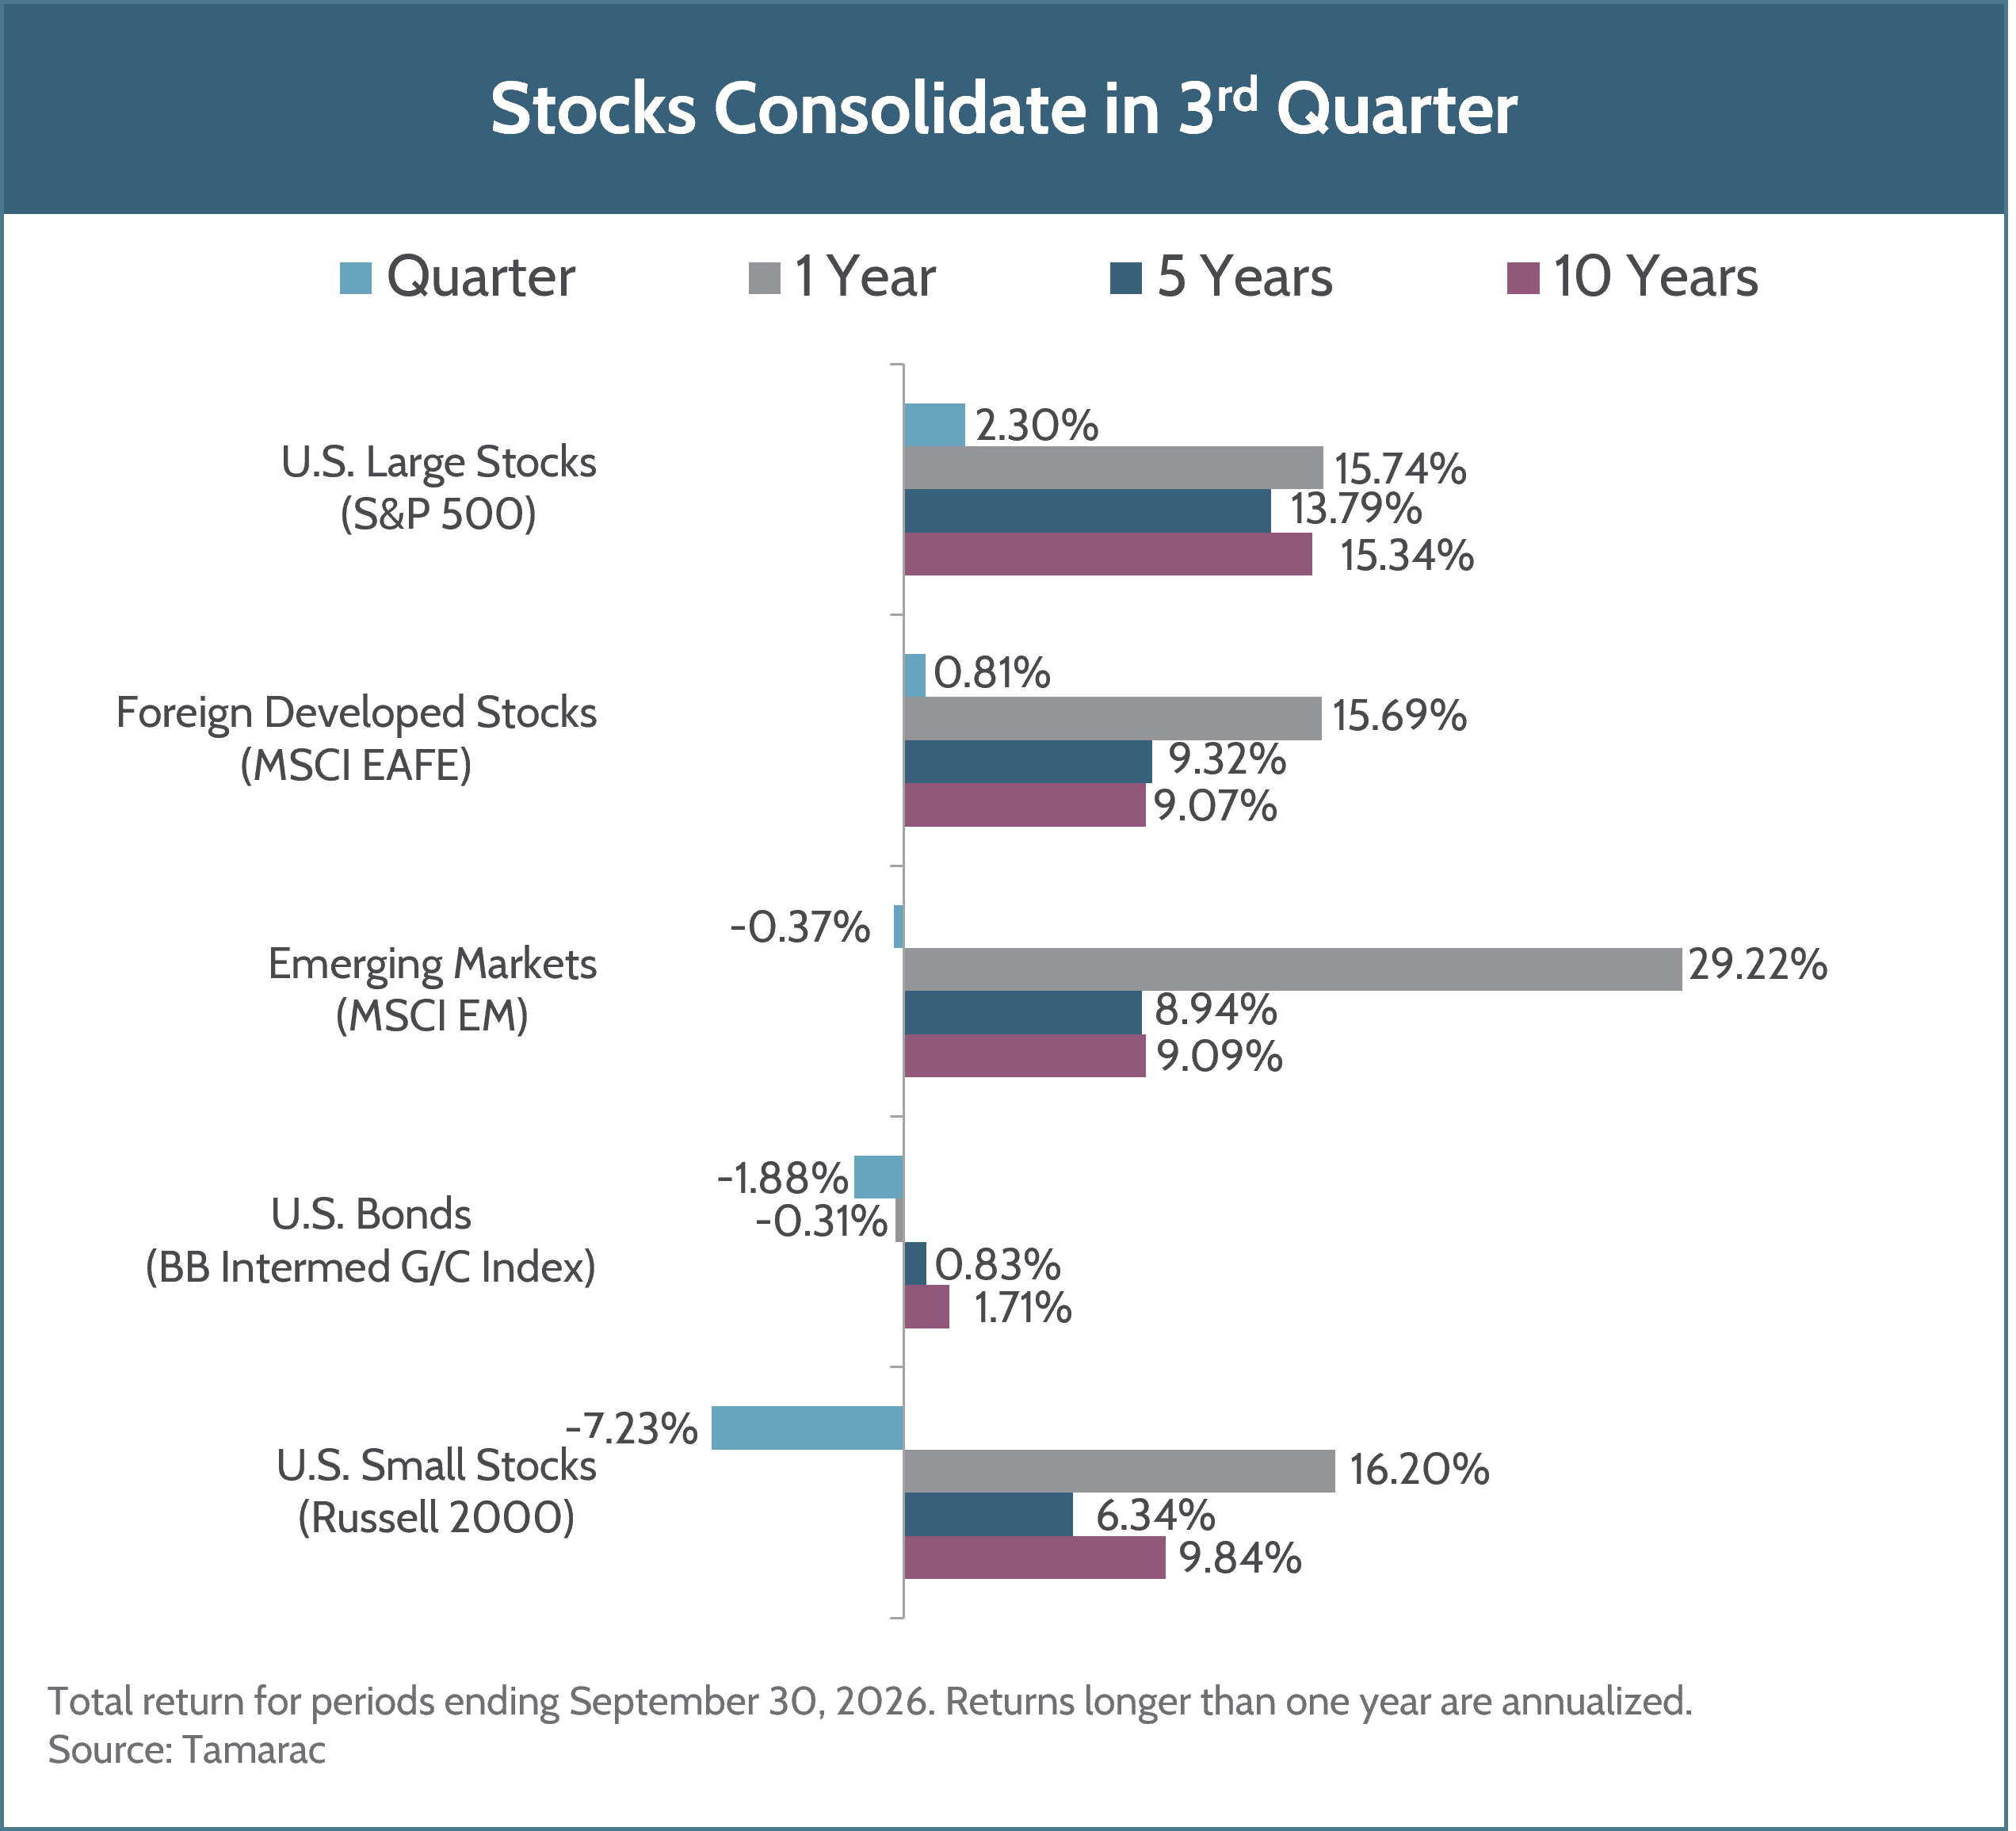
Reflecting a strong economic backdrop, driven in part by the ongoing artificial intelligence infrastructure buildout, U.S. large company earnings for the most recent quarter were exceptional. And with their stocks mostly treading water, this allowed earnings to catch up to market prices. Said differently, market valuation metrics fell without market prices falling. It is somewhat unusual to see such high earnings growth rates outside of a recovery from an economic dislocation, so it may not be surprising to see these growth rates moderate in coming quarters.
Corporate profit strength was not limited to U.S. companies. Both developed and emerging market companies also experienced meaningful profit growth. However, drivers of profit growth in these markets do share some similarity to the drivers in U.S. markets. These markets contain important parts of the semiconductor ecosystem, which benefits from the artificial intelligence infrastructure buildout.
Perhaps uncharacteristically, the action in the third quarter was in the bond market. Globally, central banks have moved to a more restrictive policy stance. The Fed raised short-term interest rates by 0.25% during the quarter, which was a nod to the ongoing economic strength and sticky inflation. It also may have served the secondary effect of reinforcing the Fed’s independence from political influence, even if that was not the explicit intention. Further out on the interest rate curve, the rate on the U.S. 10-year treasury note rose around 0.80% during the quarter, surpassing the recent highs of October 2023 and moving to the highest level in decades. This environment created a headwind for bond returns during the quarter but also potentially creates a more favorable forward-looking picture for the asset class.
Though geopolitics and upcoming elections are likely to dominate the news cycle, we remain focused on underlying fundamentals of the broad economy and corporations, and in turn the investment opportunities they present. Please reach out to your Fulcrum wealth manager if you have any questions or if there is any way we can help.
Unless otherwise noted, data presented in this report is from recognized financial and statistical reporting services or similar sources including but not limited to Reuters, Bloomberg, the Bureau of Labor Statistics, or the Federal Reserve. While the information above is obtained from reliable sources, we do not guarantee its accuracy. This report is limited to the dissemination of general information pertaining to Fulcrum Capital, LLC, including information about our advisory services, investment philosophy, and general economic and market conditions. This communication contains information that is not suitable for everyone and should not be construed as personalized investment advice. Past results are not an indication of future performance. This report is not intended to be either an expressed or implied guarantee of actual performance, and there is no guarantee that the views and opinions expressed above will come to pass. It is not intended to supply tax or legal advice, and there is no solicitation to buy or sell securities or engage in a particular investment strategy. Individual client needs, allocations, and investment strategies differ based on a variety of factors. Any reference to a market index is included for illustrative purposes only, as it is not possible to directly invest in an index. Indices are unmanaged, hypothetical vehicles that serve as market indicators. Index performance does not include the deduction of fees or transaction costs which otherwise reduce the performance of an actual portfolio. This information is subject to change without notice. Fulcrum Capital, LLC is an SEC registered investment adviser with its principal place of business in the state of Washington. For additional information about Fulcrum Capital please request our disclosure brochure using the contact information below.